
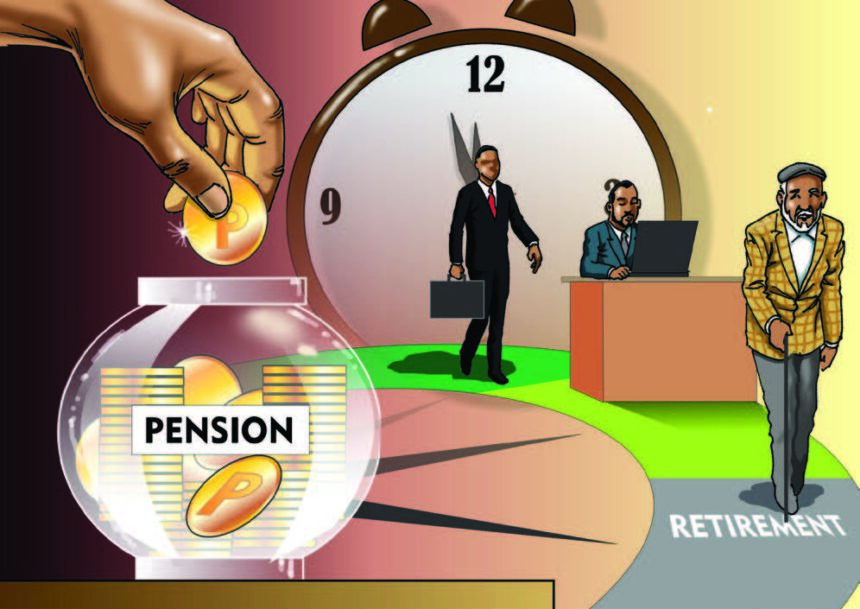
Kenya’s economy faces a conundrum, central to which is the dire state of its pension system and the burgeoning financial strain as evidenced by rising Non-Performing Loans (NPLs) within its banking sector. The plight of retirees, coupled with the financial institutions’ predicaments, paints a picture of a nation at a critical crossroads of economic stability and growth.
A recent report by Allianz has thrown Kenya’s pension system into sharp focus, ranking the country’s retirees among the poorest globally. This unfortunate standing stems from a combination of factors including inadequate pension fund mobilization, the absence of legal frameworks to delay retirement, and a skewed ratio between current contributors and future pensioners. The standard monthly contribution to the National Social Security Fund stands at a paltry Sh200, underscoring the meager support provided to retirees (Business Daily Africa).
The pension system’s inadequacy is further exacerbated by broader socio-economic challenges. As the global financial landscape evolves, Kenya’s pension schemes struggle to keep pace, affected by local factors such as corruption, inadequate legal frameworks, and the absence of robust financial planning. This leads to a scenario where the majority of those aged 65 and above are forced to continue working or live in penury, unable to enjoy a dignified retirement.
Parallel to the pension crisis, the Kenyan banking sector grapples with its own set of challenges. A significant surge in NPLs has been reported, with Fitch Ratings citing delayed government payments to contractors as a primary cause. This financial quagmire has seen the banking sector’s NPL ratio increase sharply, affecting key sectors like manufacturing and construction (Business Daily Africa).
The dual crises in the pension system and banking sector reflect deeper economic vulnerabilities. High NPLs indicate a stressed economy where businesses and individuals struggle to meet financial obligations, potentially leading to reduced lending and investment. For the pension sector, the implications are twofold: a generation of retirees faces financial insecurity, and there’s a burgeoning fiscal pressure on the government to address these systemic failings.
Addressing these challenges necessitates comprehensive reforms. For the pension sector, this could involve increasing contribution rates, improving fund management, and ensuring transparency to restore public trust. Legal and structural reforms are also needed to make the system more robust and responsive to the socio-economic dynamics of the 21st century.
In the banking sector, addressing the NPL crisis requires both policy and operational shifts. These could include enhancing the legal and regulatory frameworks to ensure timely payments for government contracts, improving risk management within banks, and fostering a more conducive business environment to reduce the incidence of loan defaults.
Kenya’s journey towards economic stability and security for its retirees is fraught with challenges. However, with strategic reforms and a commitment to addressing the root causes of its financial strains, the country can pave the way for a more secure and prosperous future.
The success of these reforms hinges on collaboration among government agencies, financial institutions, and the broader public to forge a path towards sustainable economic growth and social security for all citizens.
As Kenya stands at this crossroads, the need for decisive action has never been clearer. The nation’s ability to reform its pension and banking sectors will be a critical determinant of its economic future, impacting not only the current retirees and banking institutions but also setting the stage for the financial well-being of generations to come.